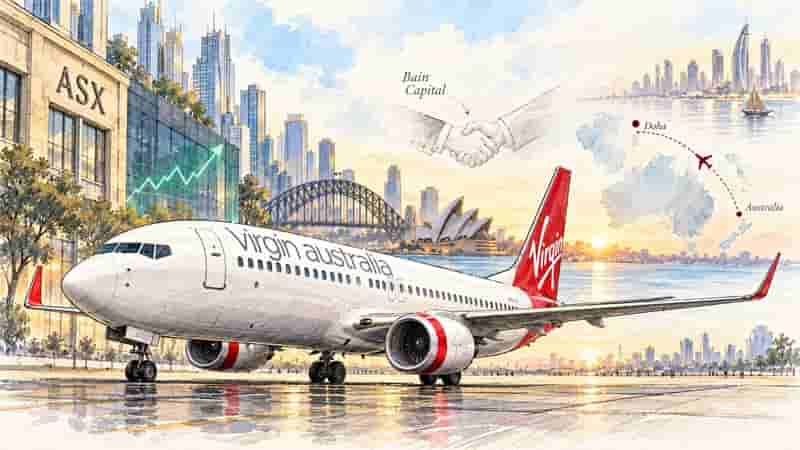
Virgin Australia’s return to the Australian Securities Exchange has delivered a remarkable turnaround for Bain Capital. But with Qatar Airways now a major shareholder, questions remain about the airline’s long-term ownership and future direction.
Virgin Australia’s remarkable journey from voluntary administration to a successful return to the Australian Securities Exchange (ASX) has become one of the most interesting aviation and private equity stories in recent Australian history.
After five years under private ownership, Virgin Australia returned to the ASX on 24 June 2025, trading under the new ticker code VGN, following a A$685 million initial public offering (IPO).
The flotation attracted strong interest from Australian and international investors, with approximately 236.2 million shares offered at A$2.90 each, representing 30.2% of the airline’s shares on issue.
The IPO valued Virgin Australia at approximately A$2.3 billion, with an estimated enterprise value of A$3.6 billion, including net debt.
However, the interesting question is not simply how Virgin Australia returned to the share market, but what its return means for Bain Capital, Qatar Airways and the future of Australian aviation.
Bain Capital’s remarkable turnaround
Bain Capital acquired Virgin Australia in November 2020 after the airline entered voluntary administration during the COVID-19 pandemic.
The transaction was widely reported at approximately A$3.5 billion, although this figure included assumed liabilities and other financial commitments rather than representing a straightforward cash payment for the airline’s equity.
Bain subsequently undertook a major restructuring, shifting Virgin Australia to a more sustainable business model and rebuilding the airline’s competitive position.
By the time Virgin Australia returned to the ASX, Bain had already sold a substantial minority interest to Qatar Airways.
The IPO gave Bain another chance to realise part of its investment, reducing its shareholding to about 40%.
Importantly, the A$685 million flotation principally involved existing shareholders selling shares. It was not primarily a capital raising intended to provide fresh operating funds for the airline.
For Bain Capital, that distinction is significant.
Private equity organisations generally invest with the intention of eventually realising their investment, rather than retaining ownership indefinitely.
Five years is certainly a substantial period in an industry as volatile and capital-intensive as aviation.
The question remains whether Bain intends to retain its substantial holding long term or progressively sell down its investment.
I suspect the latter is more likely, although Bain will determine the timing and extent of any further sale.
Qatar Airways: The strategic investor
Perhaps the most intriguing aspect of Virgin Australia’s ownership is Qatar Airways’ involvement.
Under an agreement signed in September 2024, Qatar Airways agreed to acquire 25% of Virgin Australia from Bain Capital for A$825 million.
The Australian Government approved the transaction in February 2025, and it was completed in March that year.
After Virgin Australia’s IPO, Qatar Airways’ stake was diluted to about 23.4% of the listed company.
This investment represents considerably more than a financial interest.
Qatar Airways has strengthened its commercial relationship with Virgin Australia through an integrated aviation alliance, including codeshare arrangements, loyalty program cooperation and long-haul services connecting Australia with Doha.
The Australia–Doha flights began in June 2025 under wet-lease arrangements using Qatar Airways aircraft and crews, along with opportunities for eligible Virgin Australia pilots and cabin crew to pursue secondments with Qatar Airways.
The partnership gives Virgin Australia access to a much wider international network without requiring it to make the substantial investment needed to establish its own long-haul fleet.
For Qatar Airways, it strengthens access to the Australian market and provides an established domestic partner.
The Catherine King controversy
Qatar Airways’ investment also has an interesting political dimension.
In 2023, Federal Transport Minister Catherine King rejected Qatar Airways’ application for additional international services to Australia, citing the national interest.
That decision sparked considerable controversy, with critics questioning whether the government protected Qantas from additional competition.
The Minister denied that any individual airline’s commercial interests determined her decision.
Some industry observers subsequently speculated that Qatar Airways’ investment in Virgin Australia was influenced by that earlier rejection.
However, no evidence has established that the acquisition was undertaken specifically in response to the Government’s decision.
Nevertheless, the sequence of events remains interesting.
After being denied additional services in 2023, Qatar Airways secured a substantial equity stake in Australia’s second-largest airline and deepened its commercial partnership.
From a strategic aviation perspective, that is a significant development.
Why the timing worked
Bain Capital’s decision to float Virgin Australia in June 2025 came after several years of restructuring and improved financial performance.
The airline’s subsequent results suggest that the turnaround has continued.
For the financial year ended 30 June 2026, Virgin Australia reported revenue of approximately A$6.35 billion, up from A$5.81 billion the previous year.
Statutory net profit after tax rose to about A$501.2 million, while underlying net profit after tax reached about A$404 million, up about 22%.
Virgin Australia also announced its first dividend since returning to the ASX.
These figures demonstrate the extent of the airline’s financial recovery, although rising operating costs, fuel-price volatility and competition remain continuing challenges.
Airlines are particularly exposed to economic uncertainty, geopolitical developments and fluctuations in consumer confidence.
A profitable airline today is not automatically guaranteed to remain profitable tomorrow.
What about Virgin Australia’s former investors?
Amid the celebrations surrounding Virgin Australia’s successful relisting, it is important not to forget the airline’s previous shareholders and creditors.
When Virgin Australia entered voluntary administration in 2020, its existing shareholders lost their investment.
These included major international airline groups that had previously invested considerable sums in the business.
Under the administration arrangements, unsecured creditors were expected to recover only about 9 to 13 cents in the dollar, with actual treatment depending on creditor classification.
Virgin Australia’s original ASX ticker was VAH. The relisted company now trades under VGN.
While the new listing represents a fresh chapter, the financial consequences of the airline’s earlier collapse should not be forgotten.
That history makes the recovery all the more remarkable, but it also illustrates the considerable risks of investing in airlines.
Could another international airline enter the picture?
Looking ahead, the question is whether Qatar Airways will seek to increase its shareholding or whether another international airline might eventually show interest.
Singapore Airlines was previously a substantial shareholder in Virgin Australia, while other international airlines, including Etihad Airways, also held investments before the 2020 administration.
Could Singapore Airlines return as an investor?
Might Qatar Airways seek to expand its interest if Bain eventually decides to sell more shares?
Could another international aviation group see an opportunity in Australia’s competitive domestic market?
These are possibilities to consider, not confirmed investment proposals.
Any significant future acquisition would also need to satisfy applicable Australian regulatory and foreign-investment requirements.
Moving forward
Virgin Australia has undoubtedly travelled a considerable distance since its pandemic-era collapse.
Bain Capital deserves recognition for overseeing a restructuring that returned the airline to profitability and public ownership.
Qatar Airways, meanwhile, has secured a strategic position in the Australian market through both its equity investment and commercial alliance.
For Australian travellers, the most important measure of success will ultimately be whether these developments deliver better competition, greater choice, reliable services and competitive airfares.
As for Bain Capital, I remain doubtful that owning an airline indefinitely was ever its long-term objective.
The question is not necessarily whether Bain will eventually reduce its investment further, but when, how and to whom.
And could Qatar Airways ultimately become an even more influential player in Virgin Australia’s future?
We’ll have to wait and see, but one thing is certain: the next chapter in Virgin Australia’s ownership story will be worth watching.
By: John Alwyn-Jones – © 2026.
Read Time: 6 minutes.
Author Bio:
 John Alwyn-Jones is one of those rare figures who can make the business of travel sound positively adventurous.
A lifelong communicator with the polish of a broadcaster and the curiosity of a journalist, he’s spent decades shaping stories and strategies across tourism, aviation, and the cruise world. He’s led from the front as CEO, director, mentor, and advisor, and still brings warmth and wit to every boardroom and microphone.
Known for his sharp insight into global cruise lines and destinations, John has an old-school belief in professionalism, tempered with the sparkle of someone who’s genuinely seen the world. He’s not just in the travel business; he’s made it an art form.