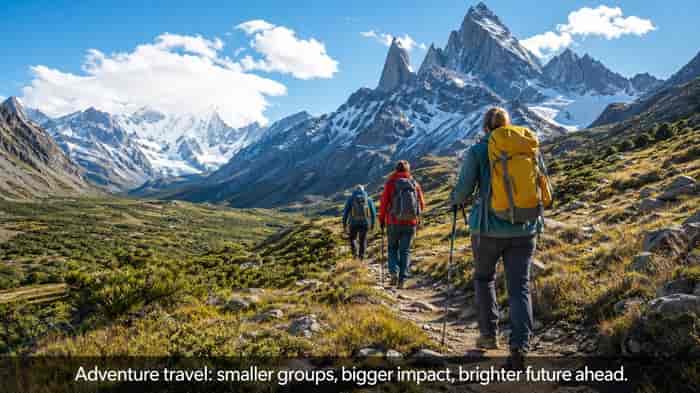
If the past few years in travel felt like a sprint, 2026 is shaping up as a long, steady walk, preferably uphill, with a decent view and fewer people.
That, in essence, is the takeaway from the latest industry readout from the Adventure Travel Trade Association (ATTA), whose 2026 Adventure Travel Trends & Insights Report suggests the sector has stopped chasing its own tail and started thinking about where it’s actually going.
After the post-pandemic surge, equal parts relief, revenge travel and a dash of chaos, the industry is easing into something more measured. Not slower in a worrying sense, but slower in the way a seasoned operator might prefer: controlled, considered, and, crucially, profitable.
Growth is still there, just without the Drumroll
Let’s be clear: the numbers haven’t fallen off a cliff. Most operators reported revenue growth through 2025. But the era of easy wins appears to be over.
Trip volumes softened. A few more operators reported declines. Margins, rather than mass, have become the battleground.
It’s the difference between filling a bus and running a business.
As ATTA CEO Shannon Stowell put it, rather neatly:
“After several years of rapid recovery, what we’re seeing now is a normalization of the sector, one that is healthier and more sustainable long term.”
Translation? The sugar hit has worn off. Now comes the proper work.
Flat fill rates hardly the stuff of headlines hint at a market that’s neither booming nor buckling. Capacity is keeping pace with demand, but not racing ahead of it. Competition is tighter. The margin for error is thinner.
Operators are responding in kind: tightening product, refining pricing, and, perhaps most importantly, resisting the temptation to grow for its own sake.
Smaller Groups, Better Stories
Here’s where it gets interesting.
The median price of popular itineraries dipped in 2025. So did average group sizes. At first glance, that looks like a warning sign.
It isn’t.
What’s actually happening is a quiet pivot from scale to substance.
Operators are trimming group sizes, sharpening experiences, and leaning into customisation. Fewer people, better delivery, stronger margins. It’s less cattle class, more curated club.
ATTA President Gustavo Timo summed it up with refreshing clarity:
“The data shows that success in today’s market is not about running bigger trips, it is about running better ones.”
There’s a certain old-school wisdom in that. Quality sells especially when travellers are increasingly wary of crowds masquerading as experiences.
At the premium end, remote and expedition-style travel continues to command healthy prices. Meanwhile, more accessible itineraries are pulling in budget-conscious travellers who still want a story to tell just without the eye-watering bill.
Different markets, same principle: give people something worth paying for.
The Local Dividend That Others Can’t Match
While mass tourism often promises economic benefits but delivers diluted ones, adventure travel continues to punch above its weight.
Around 75% of trip revenue stays in local economies. Not promised, actually retained. Add an average of $263 spent on handicrafts and souvenirs, and the impact becomes tangible rather than theoretical.
This is where the sector quietly wins.
For operators, it’s not just a moral argument; it’s commercial leverage. Destinations notice. Government’s notice. Increasingly, travellers notice.
In a market where “sustainable” is often overused and underdelivered, adventure travel has something concrete to point to.
What People Actually Want (Hint: It’s Not Complicated)
Strip away the jargon, and traveller demand hasn’t changed all that much.
Walking still leads the pack, hiking, trekking, putting one foot in front of the other, somewhere worth the effort. It’s simple, timeless, and surprisingly hard to improve upon.
But there are shifts around the edges.
Food has moved firmly into second place. Travellers aren’t just passing through destinations, they’re tasting them. Cycling, particularly via e-bikes, continues its steady rise, while cultural immersion and wellness round out the top tier.
Regional preferences add colour to the picture. Europe and North America remain fond of their e-bikes. South America sticks with hiking and food. Asia continues to draw strength from cultural depth and outdoor experiences.
Destinations are telling their own story, too.
North-East Asia and Scandinavia are back in favour, less crowded, more resilient, and offering something a little different from the usual suspects. Canada and southern South America remain strong. Western Europe, ever reliable, holds its ground.
Meanwhile, interest in the United States and Russia has softened as a reminder that geopolitics still has a seat at the table.
Sustainability: Less Talk, More Doing (Slowly)
The sustainability conversation hasn’t gone away; it’s just grown up a little.
More than half of operators now hold, or are working towards, certification. Frameworks like Travelife and B Corp are becoming standard rather than standout.
Progress, yes, but not without friction.
Cost remains a hurdle. Time, another. For smaller operators in particular, good intentions often run headlong into operational reality.
Still, the direction is encouraging. Contributions to conservation are increasing. Focus areas, such as wildlife protection, community wellbeing, and climate resilience, are becoming embedded rather than optional.
It’s not perfect. But it’s moving.
Marketing: Trust Still Beats Tech
For all the industry’s fascination with digital wizardry, the basics remain stubbornly effective.
Word of mouth leads. Always has. Probably always will.
Social media plays its part, of course. Partnerships and trade shows continue to deliver. Direct bookings dominate, but agents are quietly regaining relevance, particularly where complexity demands expertise.
Budgets haven’t ballooned. They’ve stabilised.
The difference now is intent. It’s not about shouting louder, it’s about being worth listening to.
A Sector That’s Finally Thinking Long-Term
If there’s a thread running through this year’s report, it’s discipline.
Not the flashy kind. The quiet, operational kind.
As ATTA’s Heather Kelly observed:
“The industry is becoming more disciplined, prioritizing long-term value, community impact, and operational resilience over short-term expansion.”
There’s a certain relief in that.
After years of chasing growth at a pace, the sector appears to be rediscovering the fundamentals: profitability, sustainability, and the simple idea that bigger isn’t always better.
That doesn’t mean challenges have disappeared. Political instability, regional tensions, and rising costs remain firmly on the radar. Confidence, while still positive, has softened slightly.
Yet 61% of operators expect higher net profits in 2026.
Not bad for an industry that’s supposedly slowing down.
The Bottom Line
Adventure travel hasn’t lost momentum. It’s found maturity.
The rush is over. The reckoning, if one insists on calling it that, is really just a return to sensible business.
Smaller groups. Sharper products. Stronger margins. Real impact.
Not quite as glamorous as a boom headline, but far more durable.
And in travel, durability is what keeps the lights on long after the hype has packed its bags.
Read the full ATTA report here.
by Jason Smith – (c) 2026.
Read Time: 6 minutes.
About the Author.
 Jason Smith didn’t learn travel from textbooks. He learned it in airports, taxis and hotel lobbies, watching the business unfold long before he played his own part. Half American, half Asian, he grew up around the quiet workings of tourism, where people come and go, and stories rarely stand still.
Bangkok came first, then formal study, then a career that carried him through Singapore, Malaysia and Vietnam. Each place left something behind. In the end, Thailand felt like home, and I landed a senior role in hotel sales.
Then everything stopped. Borders shut, planes grounded, and Jason found himself back in America with time to reflect.
Now at Global Travel Media, he writes travel as it really is, not polished, not perfect, but human, and all the better for it.